English
 RSS

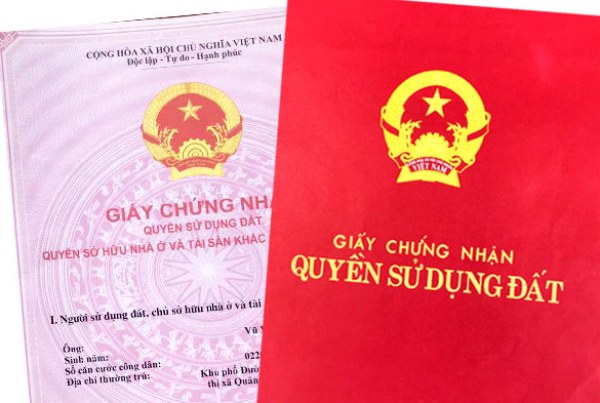
The Decree 49/2022 amends and supplements Clause 3, Article 4 of the Decree 209/2013 on the taxable price for real estate transfer.
Accordingly, the taxable price is the real estate transfer price minus (-) the land price permitted to be deducted for value-added tax calculation.
The land price permitted to be deducted for value-added tax calculation is specified as follows:
In case of land allocation by the State for investment in infrastructure to build houses for sale, the land price to be deducted for value-added tax calculation is inclusive of the land use levy payable to the state budget and expenses for compensation and ground clearance (if any).
- In the case of auctioning land use rights, the land price to be deducted for value-added tax calculation is the auction-winning land price;
- In the case of renting land to build infrastructure or build houses for sale, the land price to be deducted for value-added tax calculation is inclusive of the land rental payable to the state budget on rental and water surface rental and expenses for compensation and ground clearance (if any).
The expenses for compensation and ground clearance are in accordance with the plans which are approved by the authorized agencies and deducted for payable land use levy and land rental (new regulations).
- In the case of business establishments acquire land use rights from organizations or individuals, the land price to be deducted for value-added tax calculation is the land price at the time of acquisition, exclusive of the value of infrastructure (the previous regulations include the value of infrastructure).
Business establishments are permitted to declare and credit input value-added tax on infrastructure (if any).
(In previous regulations, business establishments are not permitted to declare and credit input value-added tax on infrastructure already included in the non-taxable to-be-deducted value of land use rights)
If it is impossible to determine the land price at the time of acquisition, the land price to be deducted for value-added tax calculation is the land price prescribed by the provincial-level People’s Committee at the time of signing the acquisition contract...
In the case it is impossible to detach the land price at the time of acquisition, the land price to be deducted for value-added tax calculation is the land price prescribed by the provincial-level People’s Committee at the time of signing the acquisition contract...
- In case of business establishments receive land use rights as contributed capital from organizations or individuals, the land price to be deducted for value-added tax calculation is the price stated in the capital contribution contract.
In case the land use rights transfer price is lower than the price of land received as contributed capital, the land price to be deducted must be the transfer price.
This Decree takes effect on September 12, 2022.