English
 RSS

1. No separate invoice is needed for VAT deduction
In accordance with the Decree No. 15/2022/ND-CP, the Government prescribed to reduce 2% of the VAT from February 01, 2022 to December 31, 2022 for goods and services which are having the VAT rate of 10%.
However, in accordance with the provision prescribed in Clause 4, Decree No. 15/2022/ND-CP on separate invoices for the goods and services eligible for VAT reduction shall apply the tax rate of 8% in accordance with enterprise’s reflect in enterprise’s increasing charges.
In particulars, accountant’s time cost and cost of using invoice for each customer increase accordingly for the reason that enterprise must make 02 invoices instead of having 01 invoice with different tax rates (5%, 8%, 10%): 01 invoice with the tax rate of 8% and 01 invoice with other tax rates (5%, 10%).
Accordingly, Article 2, the Decree No. 41/2022/ND-CP amending and supplementing this provision of the Decree No. 15/2022/ND-CP as follows:
Case 1: Business establishment applies the VAT reduction rates
Business establishments calculating VAT by the reduction method are entitled to the VAT rate must write separate goods and services in accordance with law provisions.
At that time, business establishments must write the tax rates applicable to each good or service in accordance with law provisions.
For example:
When making VAT invoices for goods and services of the goods and services which are eligible for VAT reduction, write “8%” in the VAT‘s rate column; VAT; total payable amount.
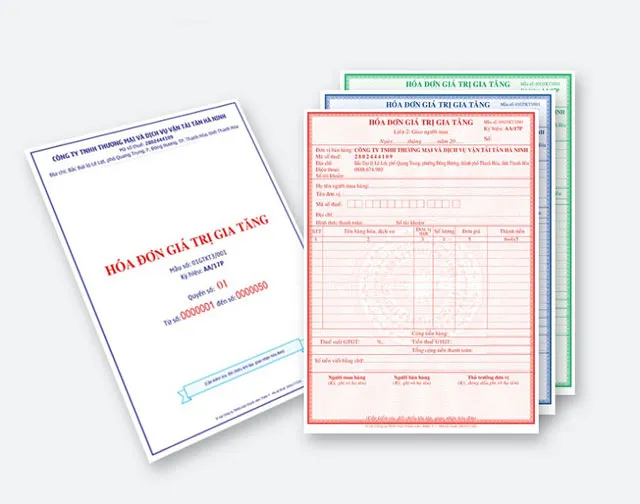
Case 2: Business establishments calculate VAT based on a percentage of their turnover
In case a business establishment calculating VAT has issued an invoice and declared tax at the VAT rate or the percentage, the seller and buyer shall make a record reduced amount in accordance with law provisions.
Write the reduced amount in the sale invoice in accordance with law provisions.
For example:
When making the VAT invoices for the objectives who are eligible for VAT reduction:
- Column “Total amount”: write the total amount of goods and services before reduction;
- Row “Total amount of goods and services”: based on the percentage of their turnover is entitled to a 20%-reduction of the percentage;
- Note: “Reduced by... (Amount) equivalent to 20% of the VAT percentage under the Resolution No. 43/2022/QH15”.
Therefore, in accordance with law provisions prescribed in the Decree No. 41/2022/ND-CP, it is not necessary to make a separate invoice for goods with VAT reduction from 10% to 8%.
2. No fines, no requirements for invoice adjustment of separate rate of 8%
In accordance with Clause 1, Article 3, the Decree 41/2022 prescribes:
From February 01, 2022 to June 20, 2022, enterprises who issue invoices with tax rate (no separate invoice for invoice with tax rate of 8%) are entitled to VAT reduction, exempted from sanctioning of administrative violations related to taxes and invoices, and not subject to invoice adjustment.
3. Apply the Notice on receipt and result of handling wrongly issued e-invoices
The Decree No. 41/2022/ND-CP issues the Form No. 01/TB-HDSS of the Notice on receipt and result of handling wrongly issued e-invoices to replace the form No. 01/TB-SSDT attached to the Decree No. 123/2020/ND-CP on invoices and documents.
Accordingly, enterprises use the new form of Notice attached to the Decree 41/2022.